
Commercial umbrella insurance adds extra liability limits above your business’s primary insurance policies.
Understanding what is commercial umbrella insurance can help you protect your company from a serious claim that exceeds the limits of general liability, commercial auto, or employers’ liability coverage. This guide explains how the policy works, what it covers, what it excludes, and how to decide whether your business needs it.
What Is Commercial Umbrella Insurance?
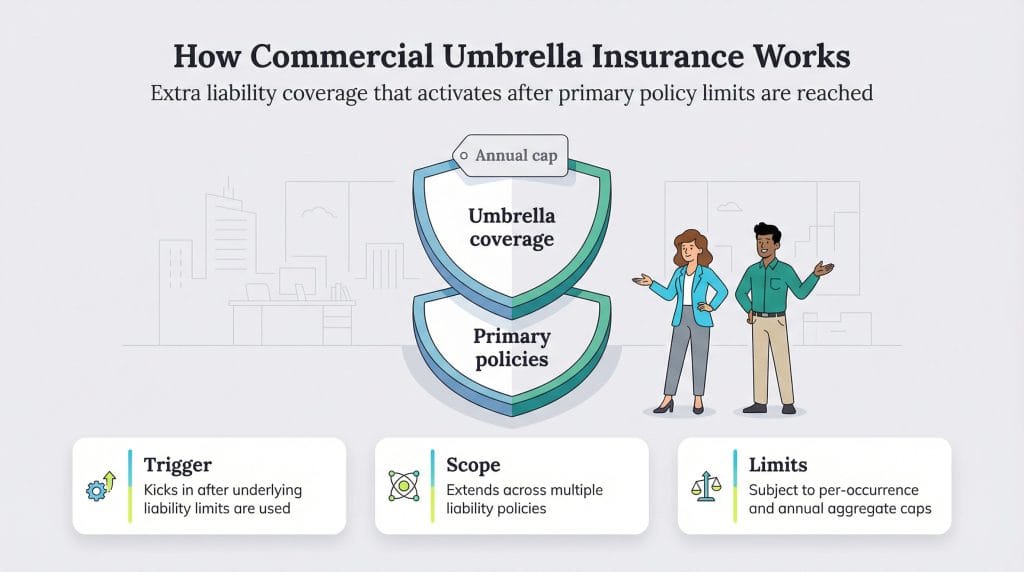
Commercial umbrella insurance is extra liability coverage for a business. It starts working when the liability limit on an underlying policy has been used up.
For example, suppose your business has a $1 million general liability limit. A customer suffers a serious injury on your property, and a court awards $1.4 million. Your general liability policy may pay the first $1 million, while a commercial umbrella policy may cover the remaining $400,000, subject to its terms.
In simple terms, a commercial umbrella policy acts like a second safety net. Your primary insurance catches most claims. The umbrella policy helps catch large claims that go beyond those limits.
The exact answer to what is commercial umbrella insurance depends on the policy wording. Some policies add only higher limits. Others may also provide broader protection for certain claims that the underlying policy does not cover, often called excess liability coverage or broader umbrella coverage.
A commercial umbrella policy usually sits above one or more underlying policies, such as:
- Commercial general liability insurance
- Commercial auto liability insurance
- Employers’ liability insurance
- Liquor liability insurance, when accepted by the insurer
- Other business liability policies listed in the umbrella policy
The umbrella insurer normally requires those primary policies to remain active. If a business cancels an underlying policy or carries limits below the required amount, the owner may have to pay part of a claim before the umbrella coverage responds.
How Does Commercial Umbrella Insurance Work?
Commercial umbrella insurance works through layers of coverage. Your primary insurance pays first. The umbrella policy may then pay after the primary limit is exhausted.
Imagine a delivery company with these policies:
- $1 million commercial auto liability limit
- $1 million general liability limit
- $2 million commercial umbrella limit
A company driver causes a crash that injures several people. The total lawsuit and settlement cost reaches $2.5 million. The commercial auto policy may pay the first $1 million. The commercial umbrella policy may then pay the next $1.5 million, assuming the claim is covered and all policy conditions are met.
The umbrella limit is often shown as a single amount, such as $1 million, $2 million, or $5 million. Some policies also have an aggregate limit. This is the most the insurer will pay for covered claims during the policy period.
A simple coverage layer example
A claim may move through coverage in this order:
- The business pays any required deductible or self-insured retention.
- The primary policy investigates and handles the claim.
- The primary policy pays up to its liability limit.
- The umbrella policy responds after the underlying limit is exhausted.
- The umbrella policy pays up to its own limit, subject to exclusions and conditions.
This layered structure explains what is commercial umbrella insurance better than the phrase “extra insurance” alone. It is not a replacement for general liability insurance. It depends on the primary policies underneath it.
What Does Commercial Umbrella Insurance Cover?
A commercial umbrella policy can cover large third-party liability claims. A third party is someone outside your business, such as a customer, visitor, vendor, or member of the public.
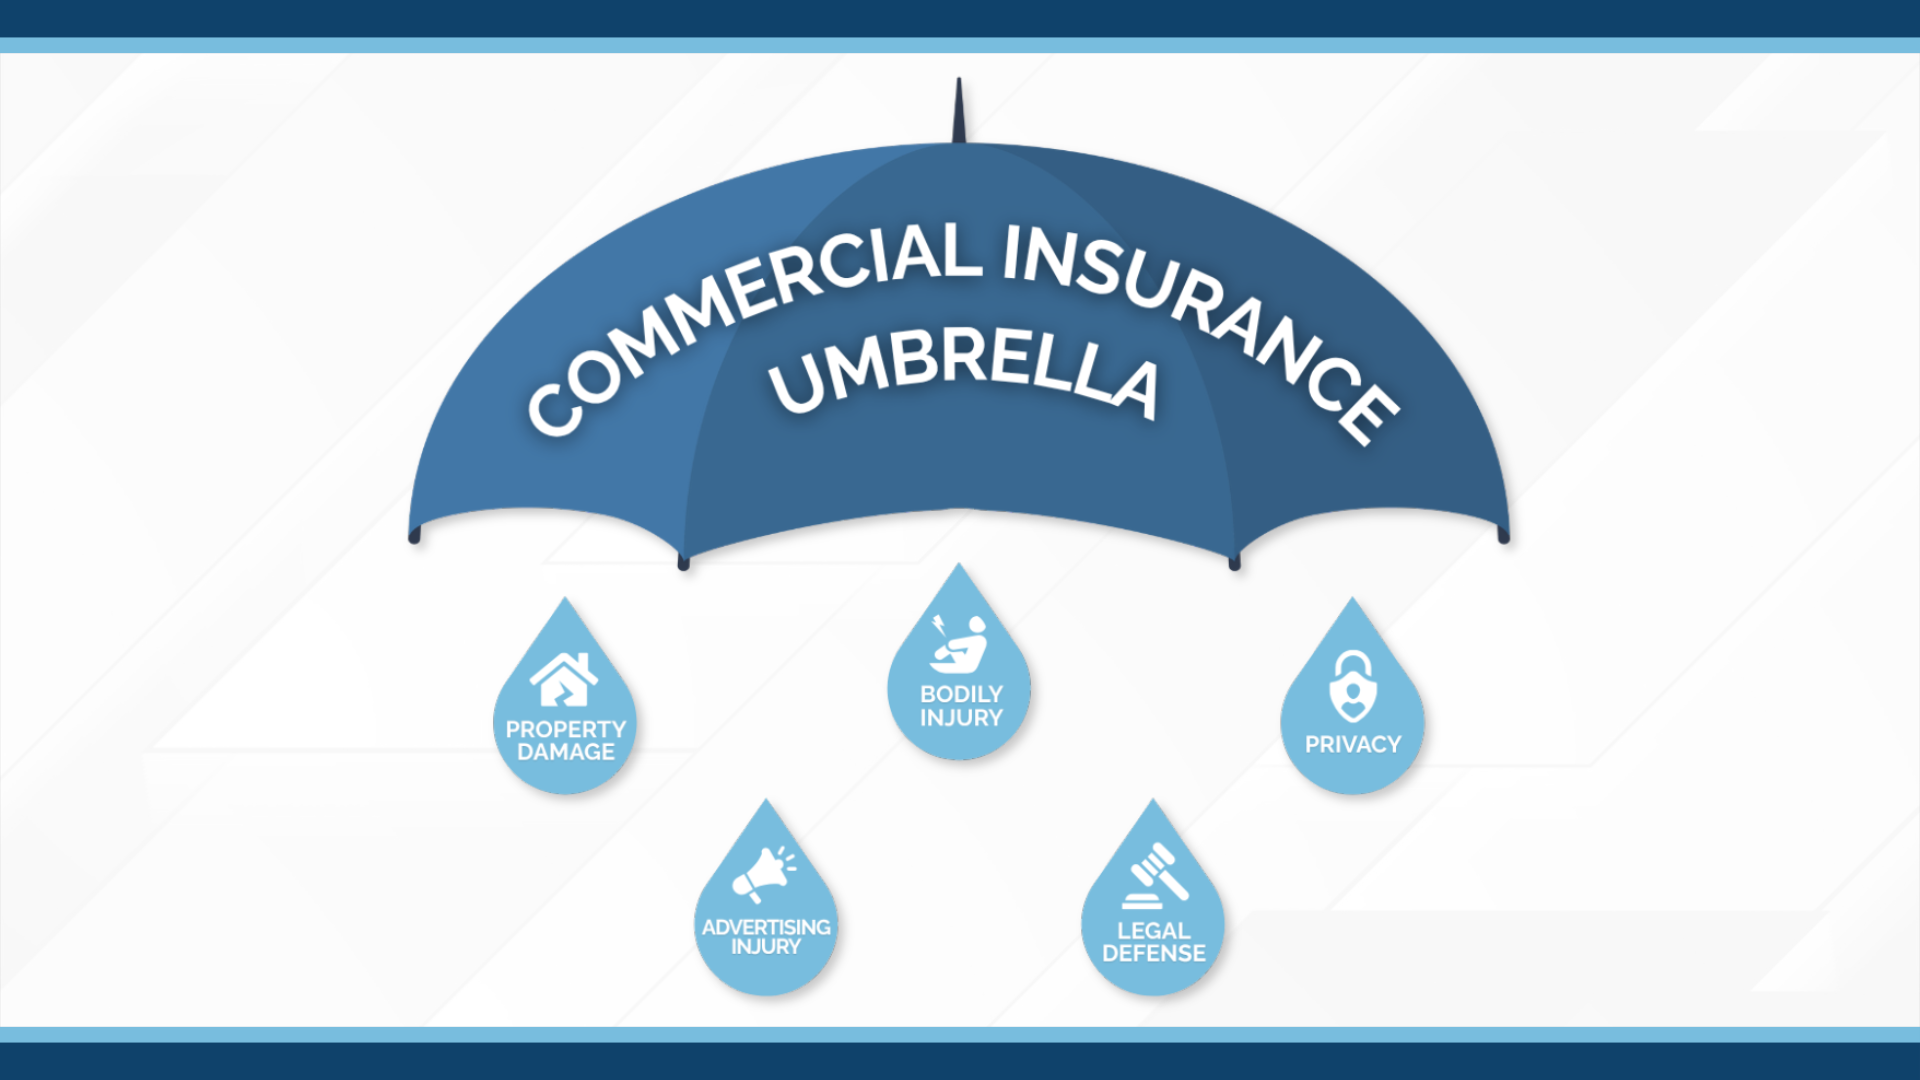
Common covered claim types may include:
Bodily injury claims
A customer could slip in a store, a visitor could fall at a work site, or a pedestrian could suffer injuries in an accident involving a company vehicle. Medical bills, lost income, legal fees, and settlement costs can grow quickly.
Property damage claims
Your company may accidentally damage a customer’s building, equipment, vehicle, or other property. If the damage is severe, the cost may exceed the limit on your general liability or commercial auto policy.
Personal and advertising injury
This can include certain claims involving libel, slander, copyright issues in advertising, or wrongful eviction. Coverage depends on the underlying policy and the umbrella policy’s wording.
Legal defense costs
Many liability policies pay defense costs in addition to the policy limit. Others may include those costs within the limit. This detail matters because a long legal case can reduce the money available for a settlement.
Claims involving multiple parties
A single event can injure many people at once. A serious fire, product defect, construction accident, or vehicle crash may create several claims from one incident. An umbrella policy can provide additional limits for these high-severity events.
Coverage varies by insurer. Always review the policy, endorsements, exclusions, and required underlying limits before assuming a claim is covered.
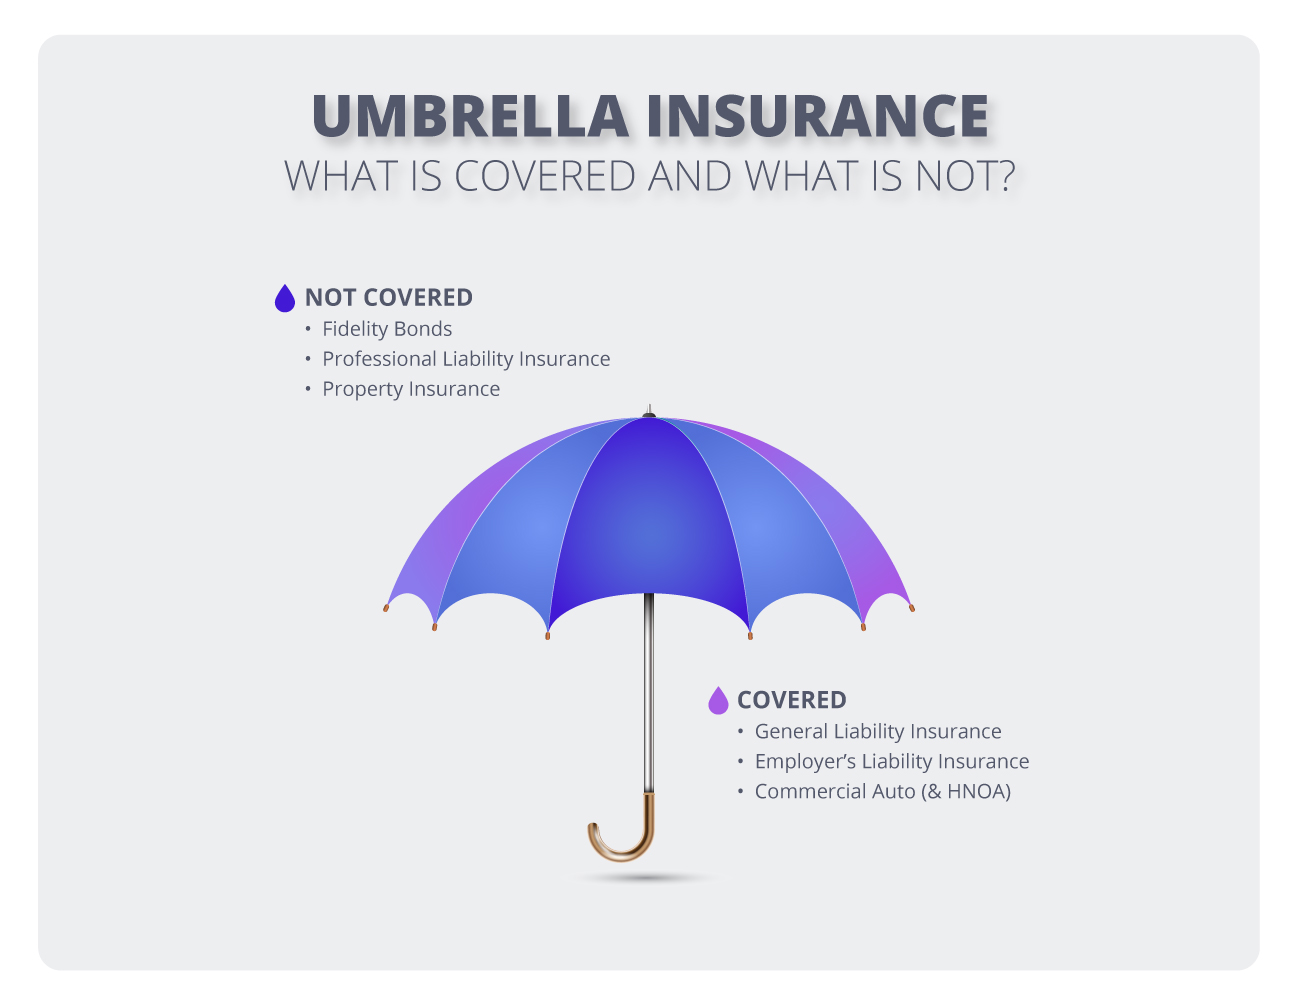
What Does Commercial Umbrella Insurance Not Cover?
Commercial umbrella insurance does not cover every business loss. It generally focuses on liability claims, not damage to your own property or ordinary business expenses.
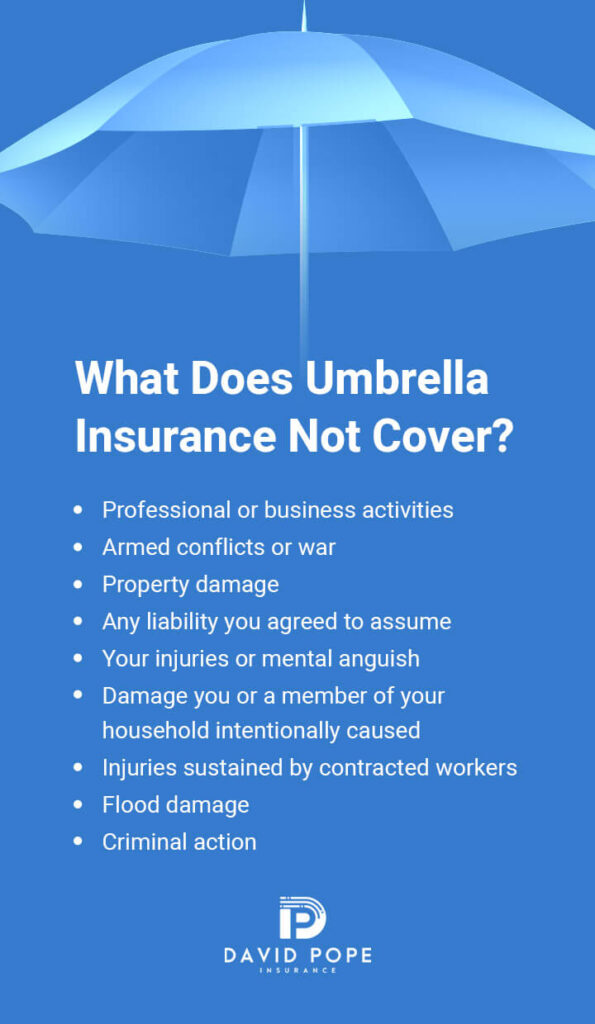
Typical exclusions may include:
- Damage to property owned by your business
- Employee injuries covered by workers’ compensation
- Professional errors covered by professional liability insurance
- Intentional or fraudulent acts
- Pollution liability, unless specifically added
- Cyber claims, unless a cyber policy or endorsement applies
- Employment practices claims, such as discrimination or harassment
- Contract disputes that do not involve covered liability
- Damage caused by uninsured activities
- Claims excluded by the underlying policy
For example, if a storm damages your warehouse, commercial umbrella insurance usually will not pay for the repairs. Commercial property insurance would be the more relevant policy.
Likewise, if a client claims your accounting error caused financial harm, professional liability insurance may respond. The umbrella policy may not apply unless the policy specifically includes that type of liability.
This limitation is one of the most important parts of what is commercial umbrella insurance. It provides more liability capacity, but it does not replace every other form of business insurance.

Who Needs Commercial Umbrella Insurance?
Any business facing a large liability claim may benefit from commercial umbrella insurance. The need is often higher when a company has valuable assets, regular public contact, employees who drive, or contracts requiring high liability limits.
Businesses that often consider umbrella coverage include:
- Construction and contracting companies
- Trucking and delivery businesses
- Restaurants and bars
- Retail stores and shopping centers
- Property owners and landlords
- Manufacturers
- Healthcare and senior care facilities
- Event and entertainment companies
- Security firms
- Cleaning and maintenance companies
- Businesses with company vehicles
- Companies that work on large commercial projects
A small business can need umbrella insurance just as much as a large company. Size alone does not determine risk. One serious accident can create a claim that is much larger than a company’s annual revenue.
Your business may especially need this coverage if:
- Customers visit your property
- Employees drive for work
- You use heavy equipment
- You work near roads, homes, or public spaces
- You handle hazardous materials
- You sign contracts requiring high liability limits
- You have substantial business or personal assets
- You want more protection from a lawsuit that exceeds primary limits
A useful way to think about what is commercial umbrella insurance is to ask this question: “Could one severe accident threaten the money, property, or future of my business?” If the answer is yes, an umbrella quote may be worth reviewing.
Commercial Umbrella Insurance vs. Excess Liability Insurance
People often use “commercial umbrella insurance” and “commercial excess liability insurance” as if they mean the same thing. They are related, but they may work differently.
Excess liability insurance usually adds more limits to a specific underlying policy. For example, an excess policy may sit above commercial auto liability and provide an additional $2 million in limits.
Commercial umbrella insurance may sit above several liability policies. It may also provide broader coverage in limited situations, depending on the policy language.
Key differences may include:
- Excess liability may follow the terms of one underlying policy.
- Umbrella insurance may cover several underlying liability policies.
- An umbrella policy may contain broader terms than the underlying policy.
- Both policies can have exclusions and required underlying limits.
- The names and features vary by insurer.
Do not choose based on the label alone. Ask the insurance professional to explain which primary policies are scheduled, what limits are required, and whether the umbrella provides broader coverage or only additional limits.
How Much Commercial Umbrella Insurance Do You Need?
There is no universal limit that fits every business. A common starting point is $1 million, but some companies buy $2 million, $5 million, or more.
Consider these factors when choosing a limit:
Your business activities
A roofing contractor, trucking company, or chemical distributor may face more severe liability exposure than an office-based consultant.
Your assets
Review business property, cash, equipment, vehicles, and other assets. Also consider whether a lawsuit could affect the owner’s personal finances, depending on the company structure and applicable law.
Your contracts
A customer, landlord, lender, or general contractor may require specific insurance limits. The contract may also require the business to name another party as an additional insured.
Your location and customer traffic
A store, hotel, restaurant, or medical facility may have frequent contact with the public. More visitors can create more opportunities for accidents.
Your vehicle exposure
Commercial auto claims can be severe. If employees drive frequently or the business owns trucks, vans, or delivery vehicles, higher liability limits may make sense.
Your risk tolerance
Some owners prefer to keep more risk on the business balance sheet. Others want a larger insurance cushion. An insurance adviser can help compare the cost of higher limits with the possible financial impact of a major claim.
A strong review looks at both the likely claim and the worst reasonable claim. Do not base the decision only on the average accident.

How Much Does Commercial Umbrella Insurance Cost?
The cost of commercial umbrella insurance depends on the business and its risk profile. A small office may pay far less than a trucking company with many vehicles and drivers.
Insurers may consider:
- Industry and business operations
- Annual sales and payroll
- Number and type of employees
- Number of company vehicles
- Driving records and vehicle use
- Claims history
- Business location
- Underlying policy limits
- Requested umbrella limit
- Safety controls and loss prevention practices
- Contract requirements
- Coverage exclusions and deductibles
Premiums can also change when the commercial insurance market hardens. In a hard market, insurers may raise prices, reduce capacity, or apply stricter underwriting rules.
Ask for quotes with more than one limit. Comparing $1 million, $2 million, and $5 million options can show the cost of each additional layer. The cheapest policy is not always the best value if it has restrictive exclusions or does not match your underlying coverage.
A Realistic Example of Commercial Umbrella Coverage
Consider a landscaping company with a $1 million general liability policy and a $2 million commercial umbrella policy. During a large commercial project, a worker accidentally damages a structure and injures two people.
The total claim reaches $2.2 million. The general liability policy pays up to its $1 million limit. If the claim is covered and the umbrella policy’s requirements are met, the umbrella may pay the remaining $1.2 million, up to its available limit.